Parcourir les catégories
Explorer
Fiverr Pro
Français
$
USD
Financial Data Scientist, Data Analyst, Financial Engineer
Are you looking for a reliable Python solution for option pricing or financial derivatives valuation?
I build quantitative finance models in Python for pricing, valuation, risk analysis, and financial engineering.
I can develop:
You will receive clean, well-structured Python code with clear calculations, visualizations, and documentation where required.
Whether you need a standalone option pricer, a university/research project, a quantitative finance model, or a custom derivatives valuation solution, I can build it around your requirements.
Tools: Python, NumPy, Pandas, SciPy, Matplotlib, Jupyter Notebook.
Please message me before ordering for complex or custom derivatives projects so I can confirm the scope and pricing.
Outils de visualisation:
Power BI
•
Python
•
Brillant(e)
•
Tableau
Industrie:
Analyse de données
•
E-Commerce
•
Services financiers
Pays cible:
Australie
•
Canada
•
États-Unis
What option pricing models do you support?
I can work with Black-Scholes-Merton, Binomial and Trinomial Trees, Monte Carlo simulation, and custom pricing approaches depending on the instrument and requirements.
Can you calculate option Greeks?
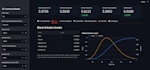
Yes. I can calculate Delta, Gamma, Vega, Theta and Rho, along with sensitivity analysis and visualizations.
Can you price exotic options?
Yes. I can work with instruments such as Barrier, Asian and other non-standard options depending on the payoff structure and available inputs.
Can you build the model entirely in Python?
Yes. The model can be delivered as clean Python scripts and/or a documented Jupyter Notebook.
Can you use Monte Carlo simulation?
Yes. I can build Monte Carlo pricing models with configurable simulations, payoff structures, convergence analysis and sensitivity analysis.
Can you calculate implied volatility?
Yes. I can implement implied-volatility calculations and related volatility analysis based on your market inputs.
Can you build a custom derivatives valuation model?
Yes. For custom products, please provide the payoff structure, contract terms, market inputs and required outputs so I can determine the appropriate modeling approach.
Can you explain the mathematics behind the model?
Yes. I can include model methodology, formulas, assumptions and a clear explanation of how the implementation works.


